Should I buy a single-family rental or a multifamily property?” is one of the most common questions new investors ask — and like most investing questions, the honest answer is that it depends on what you’re actually trying to accomplish. Single-family vs. multifamily investing isn’t a question of which is objectively better. It’s a question of which fits your capital, your risk tolerance, and how hands-on you want to be.
Financing looks completely different
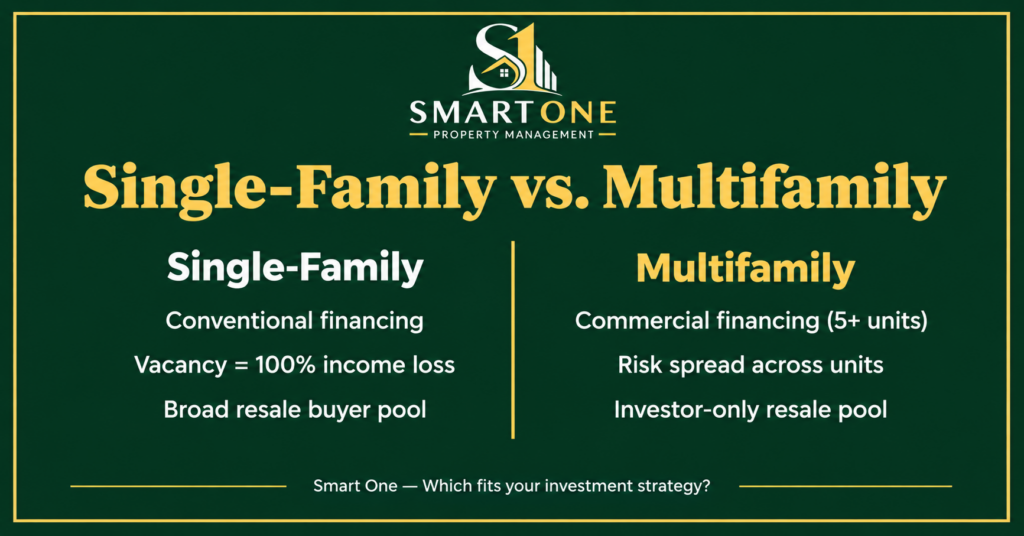
This is where the two paths diverge most concretely. Properties with one to four units qualify for conventional residential financing through Fannie Mae and Freddie Mac — the same type of loan used for a primary residence, with lower down payment options and more accessible underwriting. Once a property hits five or more units, it moves into commercial and multifamily lending territory, per Fannie Mae’s property eligibility guidelines — different qualification standards, typically larger down payments, and underwriting based more heavily on the property’s own income (NOI and debt service coverage) than on the borrower’s personal financials alone.
That threshold has real practical consequences: a duplex, triplex, or fourplex is a meaningfully easier entry point for a first-time investor than a true multifamily property, even though both technically involve “multiple units.”
Risk is distributed differently
A single-family rental is binary — it’s either fully rented or fully vacant, and 100% of the income stops the day a tenant moves out. A multifamily property spreads that risk across units: if one unit out of eight goes vacant, you’re still collecting rent on the other seven. For investors prioritizing income stability, that diversification is one of multifamily’s biggest structural advantages.
The tradeoff is concentration of a different kind — a single-family portfolio can be spread across different neighborhoods or even different cities, while a multifamily property concentrates your capital in one location, one building, and one set of local market conditions.
The buyer pool at resale is different too
Single-family homes sell into the largest possible buyer pool — both investors and owner-occupants shopping for a primary residence, which tends to support liquidity and resale value. Multifamily properties sell almost exclusively to other investors, a smaller pool evaluating the deal on cap rate and cash flow rather than emotional appeal. That’s not necessarily a disadvantage, but it does mean exit timing and pricing work differently.
Management complexity scales differently too
A single-family rental is a manageable, contained responsibility — one roof, one tenant relationship, one set of systems. A multifamily property multiplies the operational complexity: more tenants, more turnover events, more shared systems and common areas to maintain, but also more efficiency per unit, since a property manager or maintenance vendor handling eight units in one building is more efficient than the same person managing eight scattered single-family homes.
Which one fits your strategy
This connects directly to understanding your goals before making a purchase decision. An investor prioritizing simplicity, broad resale liquidity, and a lower entry cost is usually better served starting with single-family. An investor prioritizing income diversification, operational efficiency at scale, and willing to take on commercial financing and more complex management is a better fit for multifamily. Neither is the “smarter” investment in the abstract — the right one depends entirely on the strategy you’re actually running.
Weighing single-family against multifamily for your next purchase? Reach out to Smart One.
Leave a Reply