Selling an investment property usually means a capital gains tax bill. A 1031 exchange — named for Section 1031 of the tax code — lets investors defer that tax by rolling the proceeds into another qualifying property instead of cashing out. It’s one of the most powerful tools available to real estate investors, and also one of the easiest to get wrong on timing alone.
The basic idea
Instead of selling a property and paying capital gains tax on the profit, an investor sells and reinvests the proceeds into a new “like-kind” property, deferring the tax until — or unless — they eventually sell without doing another exchange. “Like-kind” is broader than it sounds: it generally covers any real property held for investment or business use, so a duplex can be exchanged for raw land, or a single-family rental for a share in a larger commercial property, as long as both sides of the trade are real estate held for investment purposes rather than personal use.
The two deadlines that make or break the exchange
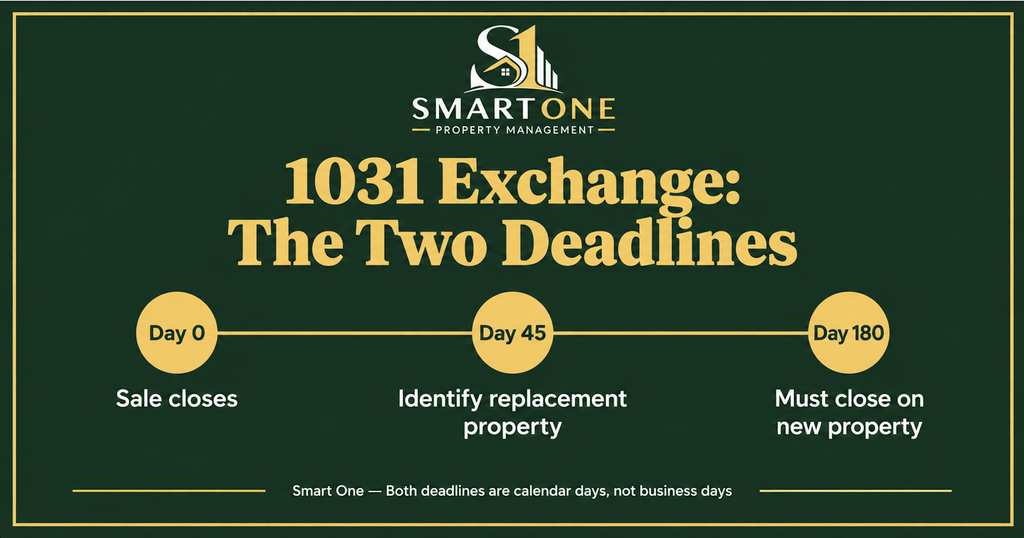
This is where most 1031 exchanges actually go wrong — not the concept, but the calendar. From the day the relinquished property’s sale closes, an investor has exactly 45 calendar days to formally identify potential replacement properties in writing, and 180 calendar days total to close on the purchase. Both deadlines run simultaneously from the same closing date, count calendar days rather than business days, and generally cannot be extended for financing delays, inspection issues, or anything else — though federally declared disaster areas have sometimes triggered automatic extensions in recent years. Missing either deadline disqualifies the exchange entirely.
The qualified intermediary requirement
An investor can’t simply hold the sale proceeds themselves between closing the sale and buying the replacement — doing so disqualifies the exchange. A qualified intermediary (QI) must hold the funds, prepare the exchange documentation, and handle the transfer at closing. The QI also can’t be just anyone: your own attorney, CPA, or real estate agent who has represented you within the prior two years is disqualified from serving in that role.
What can turn part of the exchange taxable (“boot”)
If an investor receives any cash, has debt reduced without replacing it with equivalent new debt, or ends up with non-like-kind property mixed into the deal, that portion — called “boot” — becomes taxable even within an otherwise valid exchange. A clean, fully deferred exchange generally means reinvesting all the proceeds and matching or exceeding the debt on the property being sold.
Why investors use this strategy
A 1031 exchange lets an investor upgrade, consolidate, or diversify a portfolio without losing capital to a tax bill along the way — trading a management-intensive property for a more passive one, or several smaller properties for one larger asset, while keeping the full value of the sale working for them. This is exactly the kind of goal-driven strategy we covered in our post on understanding an investor’s goals before making a recommendation — a 1031 exchange isn’t the right move for every seller, but for an investor specifically optimizing around deferring tax and staying invested in real estate, it’s often the centerpiece of the plan.
The takeaway
A 1031 exchange can be one of the most effective tools in a real estate investor’s toolkit, but the deadlines are unforgiving and the rules around intermediaries and like-kind property are specific enough that professional guidance matters. This post is for general informational purposes only and is not tax or legal advice — 1031 exchanges involve real deadlines and real consequences for getting the details wrong, so work with a qualified intermediary and a CPA before relying on this strategy for a real transaction. The IRS’s own guidance on like-kind exchanges is a good starting reference point.
Considering a 1031 exchange and want to talk through the timeline? Reach out to Smart One.