The listing photos and the neighborhood can sell you on a property before the numbers ever get a fair look. Knowing how to run the numbers before buying a rental property — in the right order, with realistic assumptions — is what separates a good purchase from an expensive lesson. Here’s a framework to work through before making an offer, not after.
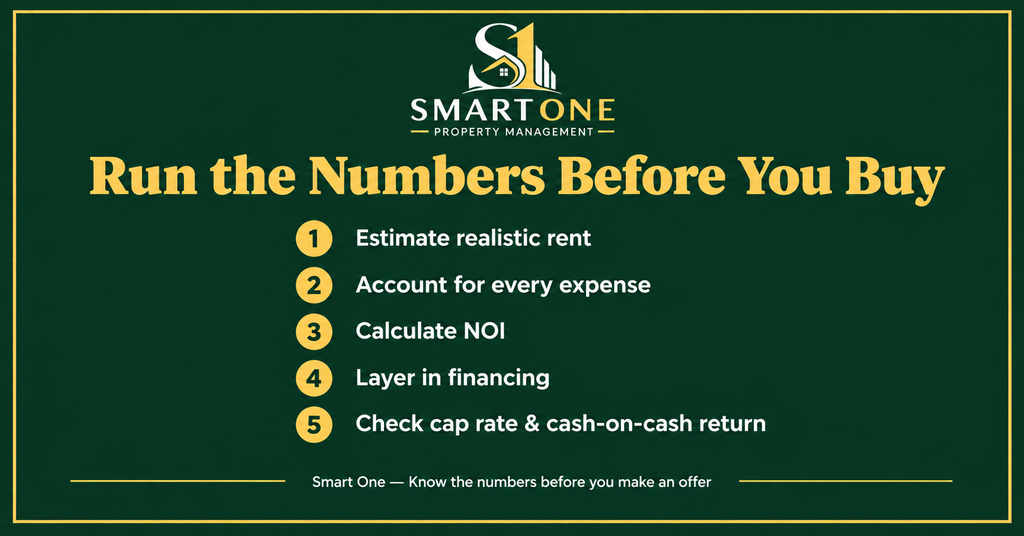
Step 1: Estimate realistic gross rent
Start with what the unit will actually rent for, not what you hope it will rent for. Pull comparable active listings for similar properties nearby — same bedroom count, similar condition, similar location — and be conservative. Overestimating rent is the single most common way new investors make a mediocre deal look great on paper.
Step 2: Account for every operating expense, not just the obvious ones
Property taxes, insurance, and any HOA dues are easy to find and easy to remember. The expenses that trip people up are the ones that don’t show up on a listing: a maintenance reserve (commonly estimated around 1% of the property’s value per year, though older properties often run higher), a vacancy reserve (budgeting for the property sitting empty part of the year, even in a strong market), and property management, typically 8–12% of collected rent if you won’t be self-managing. Skipping any of these doesn’t make the cost disappear — it just means you’ll discover it after closing instead of before.
Step 3: Calculate net operating income (NOI)
NOI is gross rental income minus operating expenses — everything from Step 2 — but before financing costs. This number is what cap rate is built on, and it’s the cleanest way to evaluate a property’s performance independent of how you’re paying for it.
Step 4: Layer in financing to find actual cash flow
Subtract your mortgage payment (principal and interest) from NOI, and what’s left is your actual monthly cash flow. This is where financing terms matter enormously — a larger down payment lowers your monthly debt service and increases cash flow, while a smaller down payment does the opposite but ties up less of your capital. Neither is automatically right; it depends on what you’re optimizing for.
Step 5: Run cap rate and cash-on-cash return
Once you have NOI and actual cash flow, you can calculate both cap rate (NOI ÷ purchase price) and cash-on-cash return (annual cash flow ÷ total cash invested) — we walked through both of these, including a worked example, in our cap rate vs. cash-on-cash return post. Running both numbers, rather than just one, gives you a fuller picture of how the property performs both on its own and specifically for your financing situation.
A quick gut-check (with a caveat)
Some investors use the “1% rule” as a fast first screen — monthly rent should be at least 1% of the purchase price — to quickly rule properties in or out before doing full math. It’s a useful filter for narrowing a long list, but it’s a rough heuristic, not a substitute for the actual calculation above; plenty of solid deals fall outside it, especially in markets with strong appreciation, and plenty of properties that pass it don’t hold up once real expenses are factored in.
Why this matters more than the listing price
Two properties at the same purchase price can perform completely differently once real numbers are run — and the property that “feels” like the better deal on a walkthrough isn’t always the one that actually performs better on paper. Running the full framework before making an offer, rather than after, is what keeps a decision based on math instead of momentum.
Working through the numbers on a potential purchase and want a second opinion? Reach out to Smart One.
Leave a Reply