California voters approved Proposition 19 in November 2020, and most people who’ve heard of it know one headline: it made it harder to pass a low property tax bill down to your kids. That’s true, but it’s only half the story. The measure also made it easier for some homeowners to move without losing their tax savings. The details inside each half are where owners and families tend to get tripped up, often years after the fact.
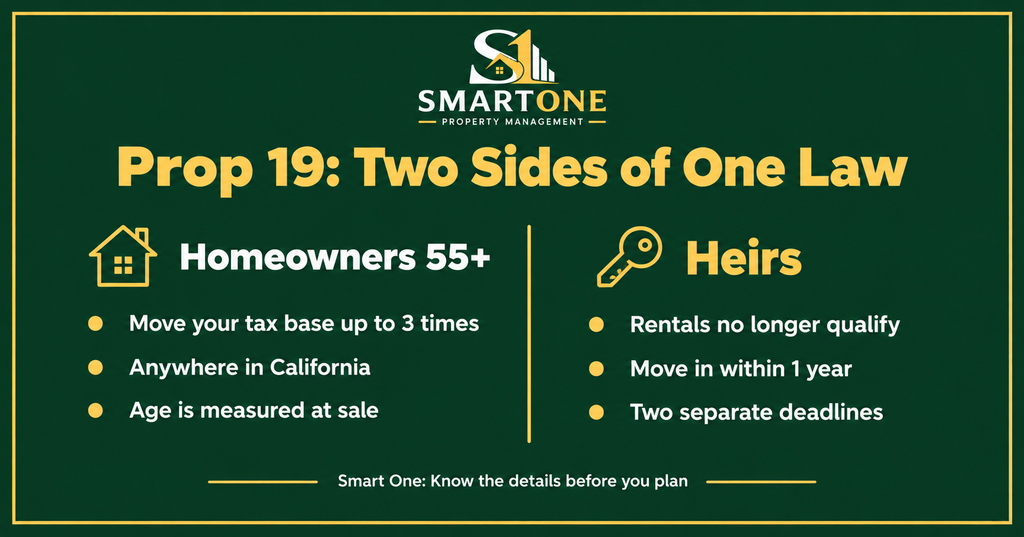
Part 1: The change that helps homeowners 55 and older
Under Proposition 19, homeowners who are 55 or older, severely and permanently disabled, or victims of a wildfire or natural disaster can transfer their existing property tax base year value to a replacement primary residence. A few details tend to get missed:
It works anywhere in California, at any price. The replacement home can be in any county, and it can cost more than the original. If it does, the difference above the original home’s value is added to the transferred base, so you don’t lose the benefit entirely; you just don’t get it on the extra value.
Age is measured when you sell, not when you buy. To qualify under the age category, you must be at least 55 when your original home sells. How old you are when you buy the replacement doesn’t matter.
You can do it up to three times. Age- and disability-based claimants can transfer their base year value up to three times, and each spouse or registered domestic partner who qualifies may claim their own three transfers.
The clock is two years. The replacement generally must be purchased or newly built within two years of selling the original home, and the claim goes to the assessor in the county where the replacement is located, within three years of the replacement’s purchase or completion.
Part 2: The change that surprises heirs
Before Proposition 19, a child could inherit a parent’s property, including rentals and second homes, without it being reassessed for property tax purposes, up to a value limit. That’s no longer the case.
Rental and vacation properties no longer qualify. The parent-child exclusion now applies only to a family home that becomes the child’s primary residence. An inherited rental, vacation home, or investment property is reassessed to current market value, even if the heir intends to keep renting it out. For owners planning to pass rental property to their children, this is the single biggest change.
Moving in isn’t enough on its own. The heir generally must move in within one year of the transfer, and must also claim the homeowners’ (or disabled veterans’) exemption within that same year. The exclusion claim itself, the BOE-19-P, can’t be filed before the exemption claim and has its own, longer deadline: within three years of the transfer, or before the property is sold to a third party, whichever comes first. Two different deadlines are easy to confuse, and a missed exemption claim can push back when the exclusion starts.
There’s a value cap, and it’s measured against taxable value. Even when the family home qualifies, the exclusion is capped at the home’s current taxable value plus $1 million, an amount that’s indexed annually. The BOE’s fact sheet lists $1,044,586 for the period ending February 15, 2027. If the home’s market value exceeds that cap, the excess is added to the taxable value, which can still mean a meaningful increase.
It can be lost. If the heir later stops using the home as their primary residence, the benefit ends. The home is reassessed as of the next lien date, generally at its fair market value on the date it was inherited, adjusted annually for inflation.
Why it matters, especially for rental owners
Here’s an illustrative example: a rental property with an assessed value of $400,000 and a market value of $1.5 million is taxed at roughly 1% of its assessed value (plus local assessments), or about $4,000 a year. After a reassessment to market value, the same base rate applies to $1.5 million, or about $15,000 a year. That’s a figure to plan for, not discover at settlement. These numbers are illustrative only; actual tax bills include local assessments and vary by property.
This connects directly to estate planning for rental property, which we covered in our post on what happens when a property owner dies in California. Who inherits, how the property is held, and whether the heir will actually live in the home are decisions that now carry real property tax consequences.
This post is for general informational purposes only and is not tax or legal advice. Proposition 19 rules have exceptions, deadlines, and indexed figures that change, so consult a qualified estate planning attorney, a CPA, or your county assessor before making decisions. The California State Board of Equalization’s Proposition 19 page and fact sheet are the best places to confirm current rules.
Own rental property and thinking through how it passes to the next generation? Reach out to Smart One Property Management.