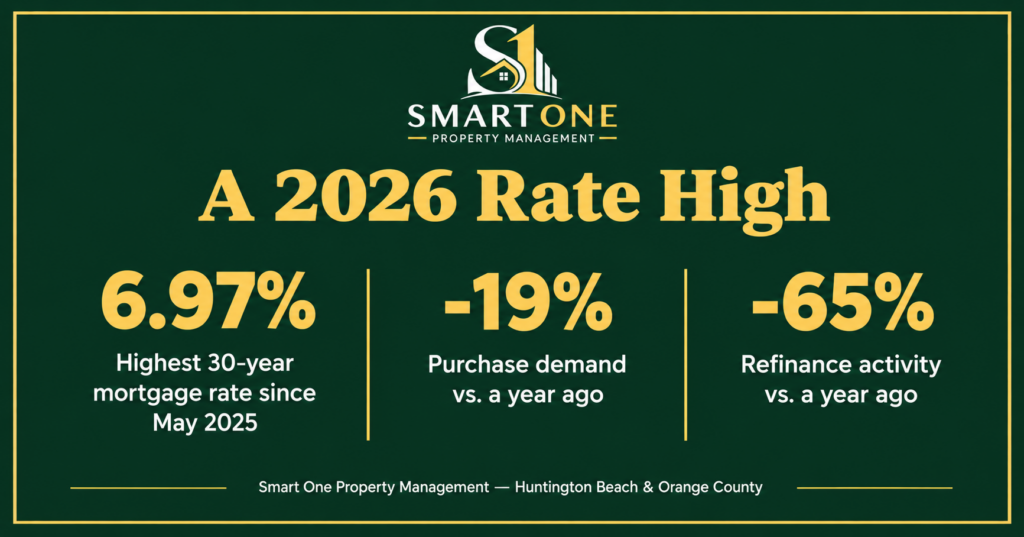
Mortgage rates climbed to 6.97% in mid-September — the highest level since May 2025 — and the latest data from the Mortgage Bankers Association shows exactly what that’s doing to demand. Total mortgage application volume fell 4.1% in a single week, purchase applications dropped another 1% and sit roughly 19% below year-ago levels, and refinance activity has nearly stalled out entirely, down 65% compared to a year ago.
Purchases: sidelined buyers, again
This continues the pattern we flagged a few weeks ago when purchase demand was already down 5% year-over-year at a 6.78% rate. Since then, rates have climbed further and purchase demand has softened further with them — a fairly direct relationship. Every basis point increase in rate pushes another slice of would-be buyers to either wait, adjust their budget downward, or stay renters for longer than they’d planned.
Refinancing has nearly stopped
The more striking number here is refinancing, now making up just 39.4% of total applications and down 65% from a year ago. This isn’t really a story about rates being “too high” in an abstract sense — it’s about the huge share of homeowners who locked in rates well below 6.97% in prior years and have zero financial incentive to refinance into something higher. Refinance activity effectively requires today’s rate to beat a homeowner’s existing rate, and for most current homeowners, it doesn’t come close.
What this means for rental owners
The purchase-side story is the more relevant one for rental property owners: as long as rates keep buyers on the sidelines, rental demand has a structural tailwind, since people who’d otherwise be buying stay renters for longer. We covered this dynamic in more detail in our earlier post on mortgage rates and rental demand — the core logic hasn’t changed, it’s just intensified as rates have climbed further this month.
The refinance freeze matters too, in a quieter way. It means existing homeowners — including rental property owners with a mortgage locked in below 5% or 6% — have very little reason to touch their financing right now. If you’re holding a rate from a couple of years ago, this environment is a reminder that your existing loan is worth more than it might feel like day to day.
What to watch going forward
Weekly mortgage data moves fast and can reverse quickly, so a single week’s numbers are a data point, not a forecast. What’s worth tracking is the trend: rates have moved from 6.78% to 6.97% in about three weeks, and purchase demand has softened alongside it each time. If that trend continues, expect rental demand to keep benefiting from buyers staying on the sidelines — but if rates reverse and start coming down, that dynamic could shift relatively quickly too.
Want help thinking through what today’s rate environment means for your specific property or portfolio? Reach out to Smart One Property Management.
Source: Mortgage Bankers Association, Mortgage Applications Decrease in Latest MBA Weekly Survey, week ending September 11, 2026.
Leave a Reply