Two investors can look at the exact same rental property and calculate two completely different “returns” — and both of them can be right. Cap rate and cash-on-cash return aren’t competing numbers. They’re answering different questions, and knowing which one matters more for a given decision is what keeps investors from comparing properties on the wrong basis entirely.
What cap rate actually measures
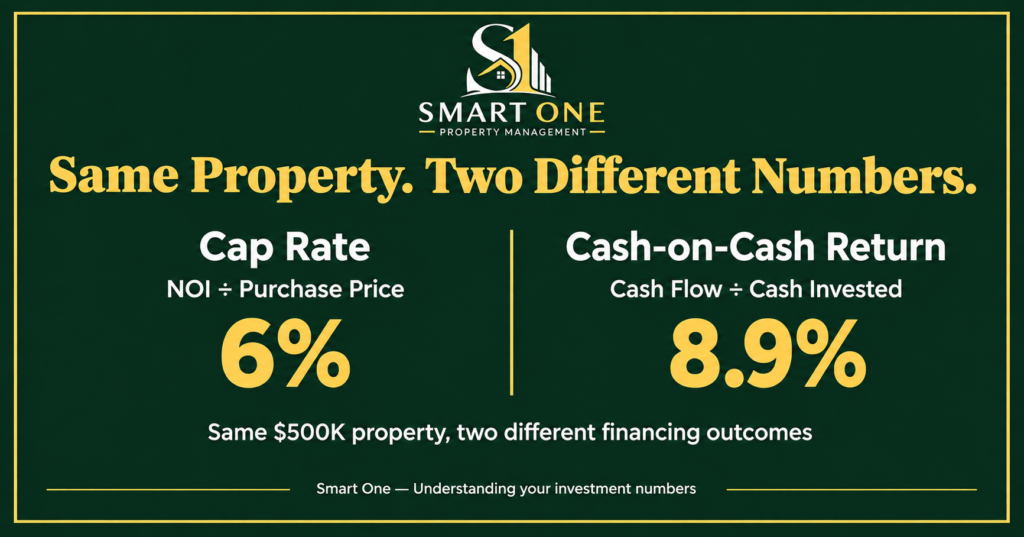
Cap rate (capitalization rate) is calculated as: Net Operating Income ÷ Purchase Price (or current market value). It tells you the return a property generates on its own, independent of how it’s financed. Two buyers — one paying all cash, one putting 20% down with a mortgage — get the exact same cap rate on the same property, because cap rate deliberately ignores financing altogether.
That makes cap rate useful for comparing properties or markets on equal footing. A 6% cap rate property and a 4% cap rate property are being compared on the underlying asset’s performance, not on who financed it more aggressively.
What cash-on-cash return actually measures
Cash-on-cash return is calculated as: Annual Pre-Tax Cash Flow ÷ Total Cash Invested. Unlike cap rate, this number is entirely about your actual financing. It answers a more personal question: given the cash I actually put in — down payment, closing costs, initial repairs — what am I getting back each year?
This is why cash-on-cash return can vary wildly between two buyers of the same property. More leverage (a smaller down payment) usually means a smaller cash investment, which can push cash-on-cash return higher — but it also means more debt service and more risk if cash flow tightens.
An illustrative comparison
Say a property generates $30,000 in annual NOI and sells for $500,000. Cap rate is $30,000 ÷ $500,000 = 6%. Now say a buyer puts 25% down ($125,000) plus $10,000 in closing costs and repairs, for $135,000 total cash invested, and after mortgage payments has $12,000 in annual pre-tax cash flow. Cash-on-cash return is $12,000 ÷ $135,000 = about 8.9%. Same property, two different numbers, both accurate — they just measure different things. (These figures are illustrative — run your own numbers based on actual financing terms and NOI for any real property.)
Which one should guide your decision
Neither number is “better” — the right one depends on what you’re trying to answer. Use cap rate when comparing properties or markets independent of financing, screening a list of potential purchases quickly, or evaluating a property you might buy in cash. Use cash-on-cash return when evaluating your actual expected return given your specific financing plan, or comparing how different down payment or loan structures affect the same deal.
This connects directly to understanding an investor’s goals before making a recommendation — a cash-flow-focused investor using significant leverage cares most about cash-on-cash return, while an investor comparing markets or planning an all-cash purchase should be looking primarily at cap rate. Using the wrong number for the decision at hand is an easy way to misjudge a deal.
The takeaway
Cap rate tells you how a property performs. Cash-on-cash return tells you how your money performs in that property, given how you financed it. A well-informed purchase decision usually looks at both, understanding what each one is — and isn’t — telling you.
Working through the numbers on a potential purchase and want a second opinion? Reach out to Smart One.